

Sandbag’s response to the public consultation on the European Commission’s EU ETS review.
On 17 July 2026, the Commission presented an amendment proposal to the ETS Directive and the MSR Decision. A public consultation ran from 25 August until 03 November.
Sandbag responded on 3 November. Read our response on the Commission’s portal here.
Ambition
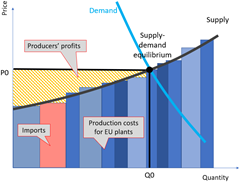
Ambition is not damaging for industry competitiveness. For the first time ever, both imports and goods made in the EU face carbon costs. The CBAM provides EU plants with pricing power, allowing them to increase their selling prices, as illustrated in Figure 1. On this figure, the price of a CBAM good (steel hot rolled coil (HRC)) increases from P0 to P1 as the supply curve shifts upwards. This has been observed in EU markets, with steel market analysts MEPS International reporting a price increase in January 2026 of 13 euros per tonne of flat steel and 9 euros per tonne of long steel,[1] well superior to the increase of net carbon costs (emissions – free allocation) for steelmakers this year.[2]
|
In 2025 (before CBAM) |
In 2026 (with CBAM) |
 |
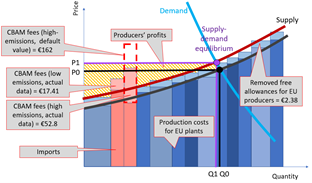 |
Figure 1: supply-demand curves of steel HRC in 2025 and 2026, including carbon costs for EU installations and imports
The price increase of steel attributed to the CBAM and EU ETS likely exceeds net carbon costs for EU manufacturers because carbon costs are relatively higher for imports than for EU plants. This effect is illustrated in Figure 2, where imports that were near the low-cost end of the merit order before the CBAM are relegated to higher-cost parts, including outside the profitable area, whereas previously unprofitable EU production becomes profitable, and the price climbs up further, to P2.
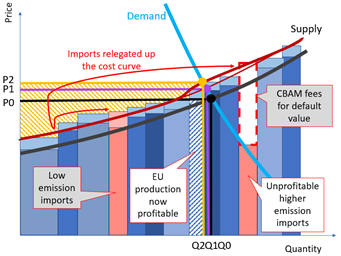
Figure 2: supply-demand curve with some imports priced out of the EU market
Installations covered by the EU ETS also benefit from EU ETS funding through the Innovation Fund. In the steel sector, 776 million euros were received by iron and steel projects and 2.8 billion euros by hydrogen projects (some of which contribute to the iron and steel industry).
By comparison, the amount of free allocation removed by the CBAM from iron and steel installations in 2026 is only worth about 230 million euros.
Summary
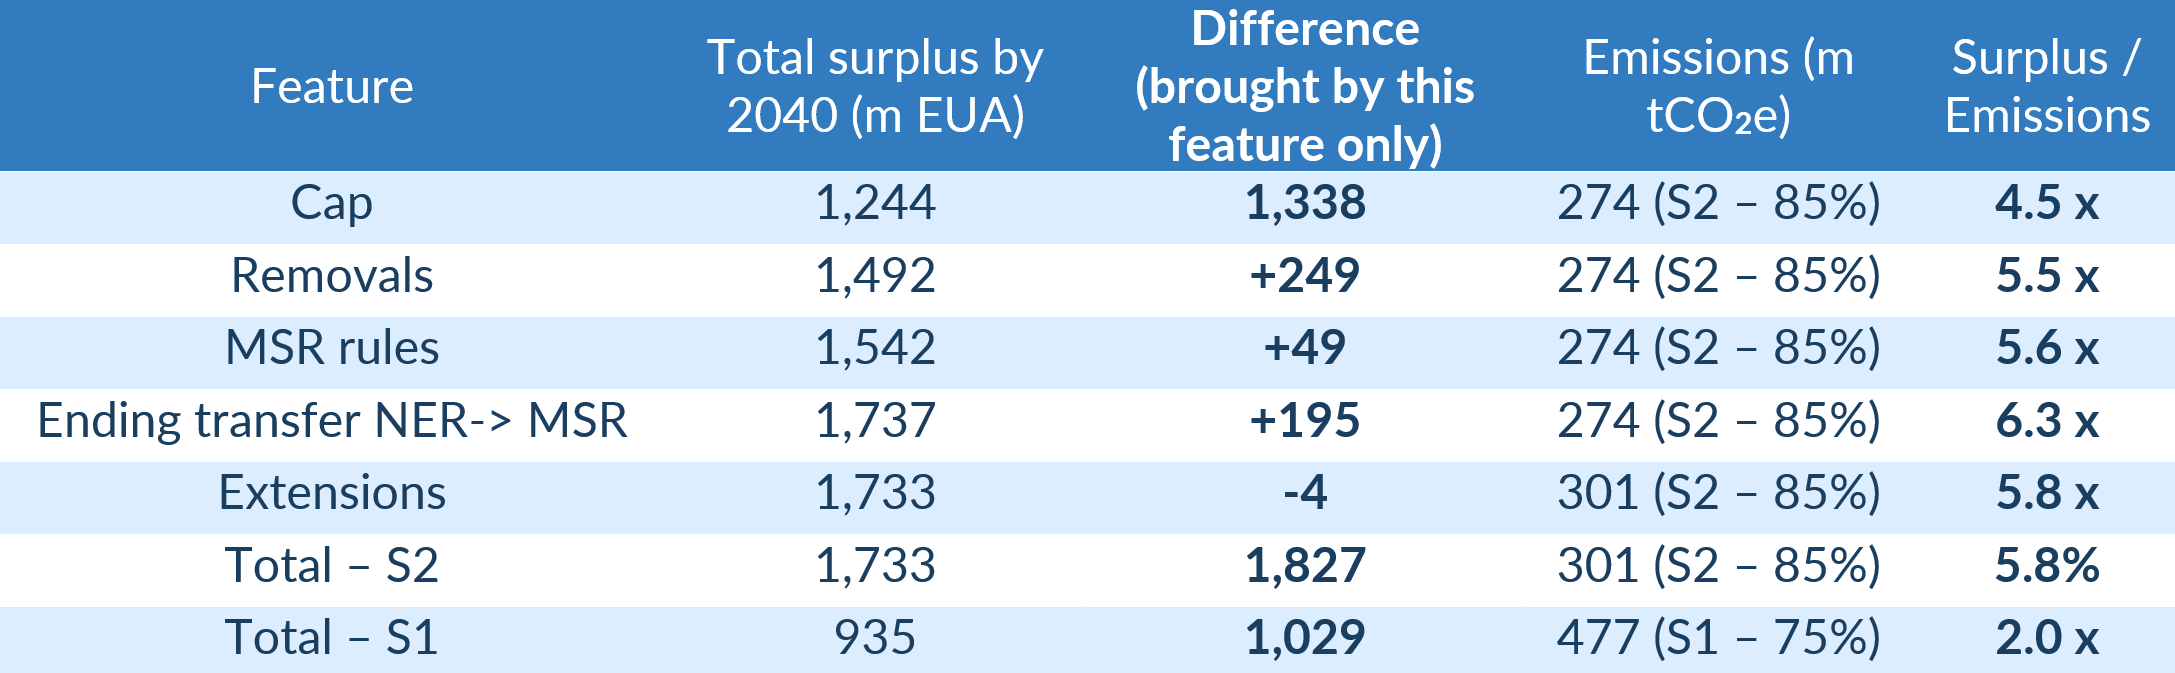
The combined design features proposed by the Commission amount to a net increase of 1,827m allowances over the period to 2040. They increase the surplus/emissions ratio from 1.7x today to 5.8x in 2040 if emissions follow the desired -85% reduction target. The ratio would be brought back to 1.7x in 2040 if emissions only follow a less ambitious -75% emissions reduction pathway.
[1] MEPS International (2026), Subdued start to CBAM era for EU steel industry
[2] Source: Sandbag (2026), The EU ETS money is coming!
Related publications
More on the EU ETS
Discussing aviation at Carbon Forward Expo London 2026
On 14 October, Sandbag’s Adrien Assous moderated a panel at Carbon Forward Expo London 2026: “Is the EU ETS delivering on its objectives? Will the proposed reforms help or hinder progress?”

Webinar: Options for the EU ETS
We presented Sandbag’s analysis of different design options for the EU ETS, and discussed proposals to mitigate potential negative impacts.

EU ETS amendments: what matters
Our position paper analyses the proposals by the Commission and EU ETS rapporteur MEP Peter Liese and presents Sandbag’s proposals.
Putting a seat belt on allowance use: how aviation could do its part
This brief proposes that access by airlines to emission allowances from other sectors should gradually be reduced.
EU ETS review: impacts on the market balance
In this brief, we analyse how the proposed changes will impact the supply and demand balance of the emission allowance market.
Sandbag responds to Thyssenkrupp
Our technical brief on how the ETS is a net benefit for European steelmakers was covered by ESG.Table, alongside a response from Thyssenkrupp Steel, which raised three objections. This response analyses the German steelmaker’s claims.
EU steelmaking: the ETS money is coming!
This brief challenges recent industry claims that EU steelmakers are being harmed by the EU’s Emissions Trading System and finds that the opposite is true.
EU ETS Reform: Let’s not invalidate climate policy!
Based on our updated EU ETS simulator, this technical brief models the impact of the several proposals on the carbon market’s supply/demand balance under the European Commission’s impact assessment emission scenarios.
Improving EU ETS benchmarks: Response to the European Commission’s public consultation on EU ETS benchmarks
Sandbag’s response to the public consultation on the European Commission’s proposed revision of the benchmark values of free allocation of emission allowances (2026-2030).
Rhetoric vs reality: setting the record straight on the impact of the EU ETS on industrial competitiveness
This brief examines whether the claims by Czechia and Italy that the EU ETS is responsible for declining industrial competitiveness hold up to scrutiny.